- Digital wallets carried 53% of UAE online payments in 2024 (Invest in Dubai). Put Apple Pay first on mobile.
- Your must-have stack: Apple Pay, Visa/Mastercard/Amex, Tabby or Tamara, and cash on delivery with confirmation.
- Published UAE card rates run from about 2.25% to 2.9% plus up to AED 1. Foreign cards cost extra, and 5% VAT applies to the fee.
- The UAE is the only GCC country with Shopify Payments and Stripe, so a UAE licence gives you the easiest start in the Gulf.
- Jaywan and Aani are the UAE's new national rails. Neither is essential at checkout yet, but plan for Jaywan by 2027.
UAE shoppers pay with Apple Pay and cards. Add a buy-now-pay-later option and cash on delivery as a fallback, and you've covered almost everyone.
That makes the Emirates the easiest payments market in the Gulf, because cash at the door is fading fast and most orders arrive already paid.
It's also the only GCC country where Shopify Payments and Stripe onboard local businesses, so a new store can take its first card payment within days.
Below, you'll see how UAE shoppers pay, which methods to switch on, what Jaywan and Aani mean for you, and what each order really costs. Notes for Shopify stores, foreign sellers and Saudi expansion come at the end.
How do UAE shoppers pay online?
Most UAE shoppers tap a wallet or enter a card. In 2024, wallets carried more than half of all online payments.
| Method | How common in the UAE | Cost to you | Do you need it? |
|---|---|---|---|
| Apple Pay, Google Pay, Samsung Pay | Most online payments, led by Apple Pay | The rate of the card inside, no wallet fee | Yes, first on mobile |
| Visa, Mastercard, Amex | Nearly every shopper, many with cards from abroad | About 2.25–2.9% plus up to AED 1, more for foreign cards | Yes |
| Tabby, Tamara | Standard in fashion, beauty and electronics | About 3–6% | Yes, for most stores |
| Cash on delivery | Shrinking fast | Courier fee plus refused parcels | As a fallback |
| Aani links, bank transfer | Invoices, social selling and B2B | Set by your bank or gateway | Optional |
A wallet isn't a separate pot of money, though. When a Dubai shopper pays with Apple Pay, there's a Visa, Mastercard or Amex card inside it.
You pay that card's rate, with no extra wallet fee. So cards are the rail, and Apple Pay is the button people press.
A few things decide how each method works for your store:
- Apple Pay. Live since October 2017, making the UAE the first GCC market to get it. It's the default on mobile, and it skips the SMS code step that makes many card payments fail.
- Visa, Mastercard and Amex. Many expats and tourists pay with a card issued back home, and foreign cards cost you more.
- Buy now, pay later (BNPL). Tabby and Tamara let shoppers split a purchase into interest-free instalments.
- Cash on delivery (COD). The shopper pays the courier in cash or by card at the door. It wins first orders for new brands, but it costs the most to run.
Which payment methods should your UAE store offer?
Offer the four things UAE shoppers expect, because each one you leave out sends some buyers elsewhere.
Here's the UAE default stack, in the order I'd show it at checkout:
- Apple Pay, with Google Pay beside it.
- Visa, Mastercard and Amex card entry.
- Tabby or Tamara (ideally both) for split payments.
- Cash on delivery, with confirmation and a small prepaid discount.
Your gateway covers the first two. Tabby, Tamara and your COD courier are separate contracts, so start those conversations early.
Why push wallets so hard? A one-tap payment converts better on a phone, and more than 75% of UAE online purchases happen on smartphones.
Jaywan and Aani: the UAE's new payment rails
Jaywan is the UAE's own card scheme, and Aani is its instant bank-transfer platform. Both are run by Al Etihad Payments, a subsidiary of the Central Bank of the UAE (CBUAE).
Neither changes your checkout today, but both will matter within a couple of years.
- Oct 2023Aani launches
Instant transfers by mobile number or QR code, up to AED 50,000 per payment.
- 2024Jaywan launches
By the end of 2024, more than 90% of shop card terminals accepted it.
- Apr 2026Jaywan goes online
Telr starts accepting Jaywan cards online. Aani passes 12.5 million users and about 774,000 merchants.
- Sep 2026More gateways add Jaywan
Checkout.com adds Jaywan, and Tap lists it on its UAE checkout.
- By end-2027Jaywan debit cards spread
Banks are expected to start issuing Jaywan debit cards widely.
- Jaywan. Few Jaywan cards are in shoppers' wallets yet. Once banks issue them widely, domestic debit should move onto Jaywan, which is designed to cost merchants less. Pick a gateway that already supports it.
- Aani. Transfers land in about three seconds, with no IBAN needed. It's great for payment links, invoices and in-store QR codes. You get it through your bank or gateway, which sets the fee.
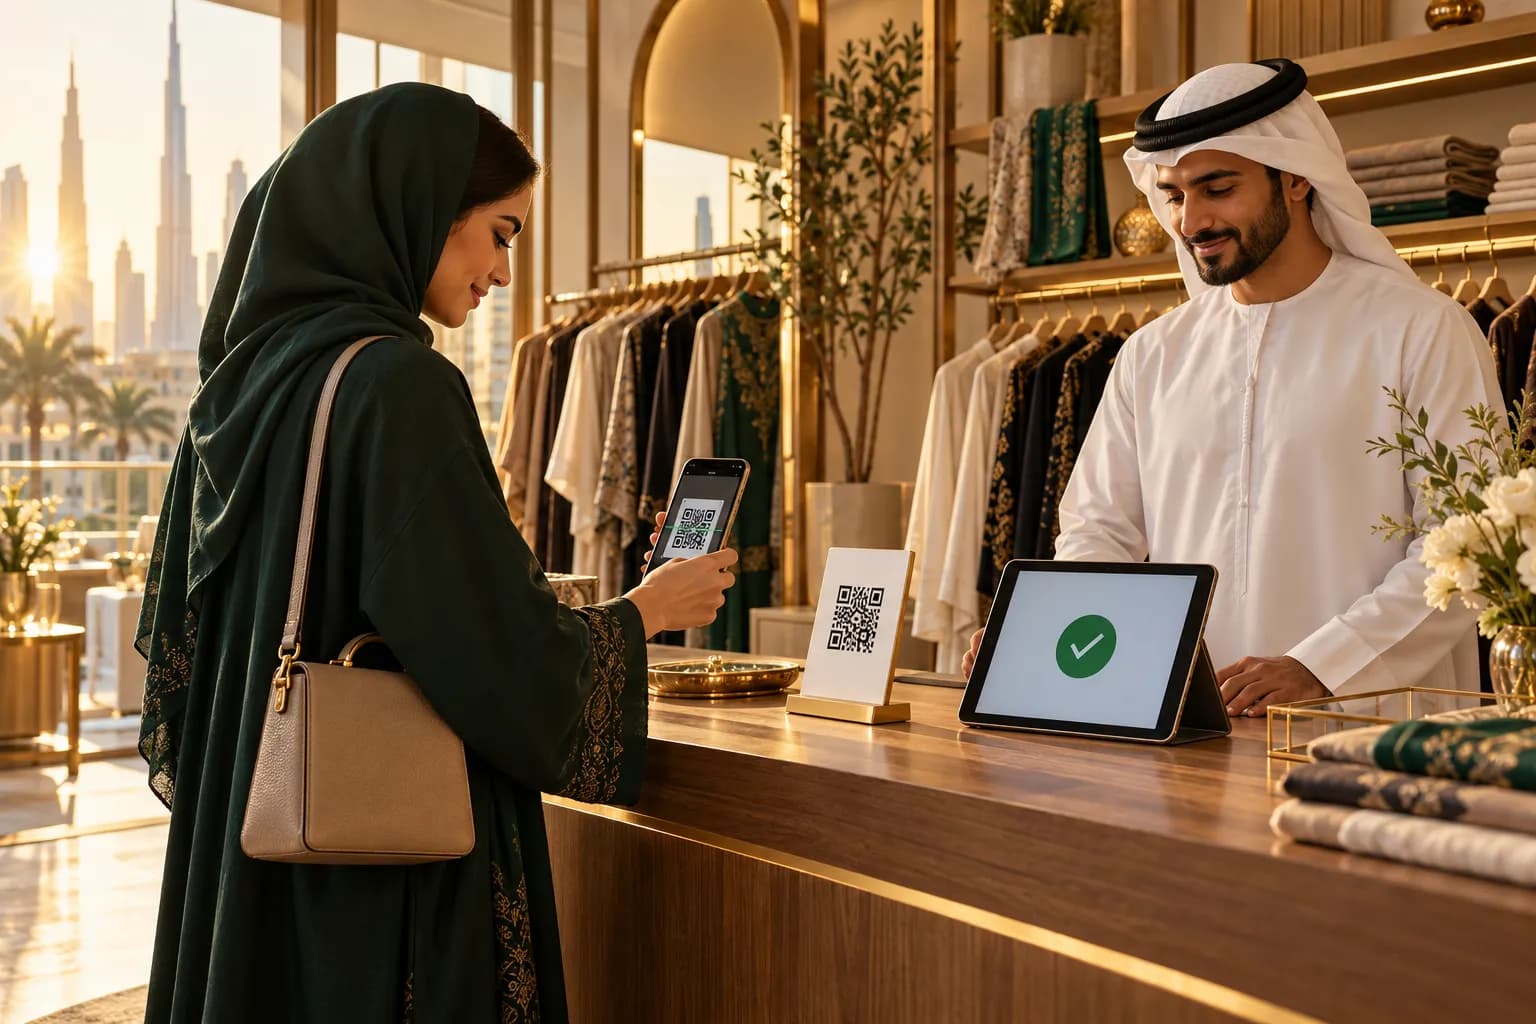
Selling on Instagram or WhatsApp? Ask your gateway whether it offers Aani payment links. For the full picture across the Gulf, see our guide to GCC payment methods.
What does it cost to take payments in the UAE?
Most UAE stores pay about 3–5% per order once everything is added up. The card rate is only the first layer.
You pay for payments in several layers:
- A percentage per payment. Published UAE card rates run from about 2.25% to 2.9%.
- A fixed fee per payment. Usually AED 0.50–1, which hurts most on cheap orders.
- A foreign-card surcharge. Cards issued abroad cost more, for example 1% extra at Stripe and 1.5% at Ziina.
- Your platform's fee. Shopify adds 0.2–2% when you use any gateway other than Shopify Payments.
- 5% VAT on the fees. VAT applies to what the gateway charges you, not to the sale.
- Extras. Monthly plans, refunds, chargebacks and instant payouts can all carry fees.
Worked example: one AED 300 order, three ways
Let's price the same AED 300 order three ways, using published rates and adding 5% VAT on the gateway fee. Telr's Small tier rate applies once you sell AED 25,000 a month, with a AED 99 monthly fee on top.
| Fee line | Shopify Payments (Basic), UAE card | Telr (Small tier) on Shopify Basic, UAE card | Stripe on your own site, foreign card |
|---|---|---|---|
| Card rate | AED 8.70 (2.9%) | AED 7.05 (2.35%) | AED 8.70 (2.9%) |
| Fixed fee | AED 1.00 | AED 0.50 | AED 1.00 |
| Foreign-card surcharge | – | – | AED 3.00 (1%) |
| Shopify's extra fee | – | AED 6.00 (2%) | – |
| VAT on the gateway fee (5%) | AED 0.49 | AED 0.38 | AED 0.64 |
| Total cost of the payment | AED 10.19 (3.4%) | AED 13.93 (4.6%) | AED 13.34 (4.4%) |
Telr has the lowest card rate of the three, but on Shopify, Shopify's own 2% fee wipes out that saving.
Foreign cards matter just as much, since the surcharge alone adds AED 3 to the order.
So check two numbers before you choose: your platform and your share of foreign cards. Our payment gateway fee calculator runs the comparison for a full month of your sales.
How do you choose a payment gateway in the UAE?
Start with your licence, then your platform, because those two decide your shortlist long before price does.
Most UAE gateways need a UAE trade licence with an e-commerce activity and an AED bank account in the same company's name. Free zone and mainland licences are treated the same.
From there, a simple rule of thumb works:
- On Shopify? Start with Shopify Payments. It's the only option without Shopify's extra fee.
- On WooCommerce or a custom site? Compare Stripe, Telr and Ziina on your own numbers. Our guide to Stripe in the UAE covers what it does and doesn't support.
- Selling AED 500,000 a month or more? Ask the large acquirers for a custom quote.
- Selling across the GCC? Look for a gateway that also handles mada, KNET and other local debit networks.
Ask every gateway for a written rate card, including the foreign-card line, the payout cycle and any reserve. Then compare all of them in our directory of payment gateways in the UAE, with published fees and onboarding rules.
Buy now, pay later: should you add Tabby and Tamara?
For most stores, yes. BNPL lets shoppers split the price into instalments while you get paid upfront, and it lifts basket size most in fashion, beauty and electronics.
Tabby reports 25 million users and Tamara about 20 million across the Gulf. Their users overlap, and shoppers stick with whichever app holds their credit limit. That's why many UAE stores offer both.
The cost is higher than cards, and neither publishes merchant rates. Sellers typically report about 3–5% for Tabby and 4–6% for Tamara, depending on category and volume.
Know the UAE rules before you switch it on:
- Credit cap. CBUAE rules limit a shopper's BNPL credit to AED 20,000 or three months' income, over 12 months at most.
- No legal minimum basket. Providers and merchants set their own minimum order, so you can choose yours.
- Fee cap for shoppers. Total fees, including late fees, can't exceed 30% of the amount borrowed.
Compare fees, payouts and Shopify apps in Tabby vs Tamara, or get quotes from BNPL providers in the UAE.
Cash on delivery: is it still worth offering?
As a fallback, yes. COD helps a new brand win its first order from shoppers who don't know it yet.
But it's expensive. Many UAE merchants see 20–35% of COD parcels refused or returned before they fix their process, and you pay shipping both ways on each one.
So keep COD, but control it:
- Confirm every order on WhatsApp before it ships. One UAE courier reports this cuts returns by 10–15 percentage points.
- Reward prepaid. AED 5–10 off for paying online moves many buyers to Apple Pay.
- Require a landmark or building name. Unclear addresses are a top cause of failed deliveries.
- Negotiate remittance. Couriers hold your cash until they pay out, so get a fixed cycle, such as 7 days, in writing.
With confirmation in place, a COD-heavy UAE store should land at about 8–15% returns. Run your own numbers in our guide to cash on delivery in the GCC.
Chargebacks, fraud and 3D Secure
A chargeback is when a shopper asks their bank to reverse a card payment. The bank pulls the money back from you, and the gateway adds a fee, such as AED 60 per dispute at Stripe.
3D Secure (3DS) is the extra check, usually an SMS code or a banking-app prompt, that confirms the cardholder is real. It's standard for UAE cards.
Keep it switched on, because when a 3DS-verified payment turns out to be fraud, liability usually moves to the card issuer instead of you.
UAE checkout payment checklist
Notes for Shopify stores
- Use Shopify Payments. It's live in the UAE, and nowhere else in the GCC. It needs your UAE licence and an AED account with an IBAN starting "AE".
- Know what it covers. Visa, Mastercard, Maestro, Apple Pay, Google Pay and Shop Pay, online only.
- BNPL still pays Shopify's fee. Tabby and Tamara install as separate apps, so Shopify adds 2% on Basic or 1% on Grow to those orders.
- COD is free on Shopify's side. It's a manual payment method, so Shopify adds no transaction fee.
Plans, payouts and setup are in our guide to Shopify in the UAE.
Notes for foreign and Chinese sellers
- Start on a marketplace. Amazon.ae and noon collect every payment method and pay you out abroad.
- Your own store needs a UAE entity for local gateways and Shopify Payments. A free zone company can be 100% foreign-owned.
- Cross-border acquirers work too. They can charge UAE cards and settle abroad, but expect higher fees.
- Price in AED. Shoppers trust it, and BNPL settles in dirhams.
Notes for sellers expanding to Saudi Arabia
- Your UAE gateway can charge Saudi cards, but mada cards go through as Visa or Mastercard, with more declines.
- Domestic mada needs a Saudi entity and a SAMA-licensed gateway.
The full Saudi playbook is in payment methods in Saudi Arabia.
Why now is a good time
UAE payments keep getting easier and cheaper. Wallets are now the majority, COD keeps shrinking, and two national rails are coming online.
Jaywan should push down the cost of domestic debit, while Aani is already giving shoppers instant bank payments.
Set up the right stack now, and you'll catch that shift from day one. For every other Gulf market, head back to our payments hub.
Frequently asked questions
For a local gateway or Shopify Payments, yes. They need a UAE trade licence, mainland or free zone, plus an AED bank account in the same name. Without one, sell on Amazon.ae or noon, which collect payment for you, or use a cross-border acquirer that settles abroad.
Sources & further reading
- Dubai's ecommerce market to reach $13 billion by 2029 (Invest in Dubai data) — Digital Commerce 360
- 4th annual MENA report: cash on delivery usage halved — Checkout.com
- Aani: 12.5 million users and instant transfers in 3 seconds — Al Etihad Payments
- Jaywan — Wikipedia
- Stripe UAE pricing — Stripe
- Telr pricing — Telr
- Shopify Payments supported countries — Shopify Help Center
- CBUAE regulatory framework for short-term lending (BNPL) — Hadef & Partners
This guide is for general information only and is not legal, tax or financial advice. Rules and fees change — always confirm with the official source or a licensed advisor.
Maya is MiddleEastEcom's lead guide and editor. She researches GCC marketplaces, payments and regulations and turns them into practical playbooks for sellers.
Meet Maya